Rose Street Advisors Rose Street Advisors
Firm
About UsOur TeamM Financial GroupEducation LibraryCommunity SupportTestimonials
Benefits
Employee Benefit ServicesBenefits FAQBenefits University Blog
HR Consulting
HR Consulting ServicesHR BlogRose Street Recruits
Life Insurance
Life Insurance ServicesLife Happens BlogLife Insurance Vlog
Employer Retirement Plans
Retirement ServicesFiduciary Fitness ProgramGuide to Retirement BlogRetirement Plans FAQ
Wealth Management
Wealth Management ServicesInvestED BlogWealth Management FAQs
Get In Touch

Retirement, HSA, and Estate Updates at a Glance

As the calendar turns, the numbers shift — and with them, meaningful opportunities to strengthen retirement plans, optimize taxes, and plan for the next generation. The IRS has released the updated limits for 2026, and while many changes appear modest, they can add up to powerful long-term advantages for savers, investors, and families preparing for wealth transfer.

2025 vs 2026: Key Retirement, HSA, Estate, and Tax-Savvy Updates

Account / Rule

2025 Limit

2026 Limit

Why It Matters

401(k) / 403(b) / 457 employee deferral

$23,500

$24,500

More room for pre-tax or Roth savings.

401(k) Catch-Up (50+)

$7,500

$8,000

Extra boost for those nearing retirement.

Super Catch-Up (60–63)

$11,250

$11,250

Additional employee-only savings opportunity.

Combined Employee + Employer (§415)

$70,000

$72,000

Larger cap helps business owners and self-employed individuals.

Traditional / Roth IRA (under 50)

$7,000

$7,500

Modest increase enhances tax-advantaged growth.

IRA Catch-Up (50+)

$8,000

$8,600

Higher limit for late-career savers.

HSA (Self-Only)

$4,300

$4,400

Helps fund medical + retirement needs.

HSA (Family)

$8,550

$8,750

Slight bump for families.

HSA Catch-Up (55+)

$1,000

$1,000

Still a valuable tool for older savers.

Annual Gift-Tax Exclusion

$19,000

$19,000

Predictable gifting; couples can give $38,000.

Qualified Charitable Distribution

$108,000

$111,000

Tax-efficient giving directly from IRAs.

Charitable Giving for Standard Deduction filers

N/A

$1,000 Single/$2000 Married

Cash donations deductible even without itemizing.

529 → Roth IRA Conversion

Allowed up to $35,000 lifetime

Allowed up to $35,000 lifetime

Turns unused 529 funds into retirement savings.

Estate Tax Exemption (individual)

$13.99mm

$15mm

Higher threshold for tax-free transfers.

Estate Tax Exemption (married)

$27.98mm

$30mm

Expanded room for multi-generational planning.

What These Changes Mean for You

 1. More Room For Retirement Savings

Higher limits across 401(k)s, IRAs, and HSAs create more tax-efficient space for long-term wealth building. For example, a saver age 60–63 could potentially contribute up to $35,750 in employee-only 401(k) contributions — and up to $72,000 when combined with employer dollars.

 2. Strategic Charitable Giving Options

QCD limits rise to $111,000 in 2026, making it easier for IRA owners 70½+ to give generously while reducing taxable income. Even standard-deduction filers can deduct up to $1000 for single/$2000 for married filing jointly in cash/stock donations next year.

3. New Flexibility for 529 Plans

Unused 529 dollars can now be moved into a Roth IRA for the beneficiary, giving families a tax-efficient way to support a child or grandchild’s retirement — provided the account is old enough and earned-income rules are met.

4. Expanded Estate and Legacy Planning Power

With the 2026 exemption rising to $15 million per individual ($30 million per couple), families have additional room to transfer wealth tax-free. Paired with annual gifting and charitable strategies, this strengthens multi-generational planning.

5. A Holistic Planning Opportunity

Retirement accounts, HSAs, charitable tools, and estate strategies don’t stand alone — they work together. Thoughtful coordination can create more tax efficiency and better long-term outcomes.

Even small annual changes can have major lifetime impact. The 2026 updates offer more ways to save for retirement, strengthen philanthropic plans, manage healthcare expenses, and pass wealth efficiently to heirs. With a coordinated approach, these expanded limits help protect both lifestyle and legacy.


As the financial landscape evolves, staying proactive ensures your planning keeps pace. Use the new 2026 limits to your advantage — and position yourself and your family for a stronger financial future.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5057537

Interested in more?

Let's Talk Proactive HR
As 2025 comes to a close, taking a few strategic steps now can help reduce your tax liability and position you for a stronger financial year ahead. Beyond just contributions and deductions, savvy planning can include gifts, income timing, and leveraging credits. Here’s the top 7 ideas for the 2025 year-end.

1. Maximize Retirment Contributions

Contribute to retirement accounts like 401(k)s, IRAs, and HSAs to lower taxable income: 

- 401(k): Up to $30,500 (including catch-up contributions for those 50+)

- IRA: Up to $7,000 ($7,500 if 50+)

- HSA: $4,300 for individuals, $8,550 for families

These contributions not only reduce taxes today but also grow tax-deferred (or tax-free for Roth accounts).

2. Utilize Tax-Loss Harvesting

Selling investments that have declined in value can offset capital gains from other investments. This strategy, known as tax-loss harvesting, allows you to reduce taxable income by up to $3,000 in excess losses.

Carryover of Losses:
If your total net capital loss exceeds $3,000 ($1,500 if married filing separately), the remaining loss can be carried over to future tax years. You can apply it against future capital gains, and if any amount remains, up to $3,000 per year can continue to offset ordinary income until the loss is fully used. This allows investors to gradually use larger losses without losing the tax benefit.

3. Accelerate Deductions & Defer Income

- Accelerate Deductions: Prepay medical expenses, property taxes, or charitable contributions this year to reduce taxable income (if you are itemizing on your taxes).

- Defer Income: Delay bonuses, consulting income, or other earnings to next year if you expect a lower tax bracket.

4. Review Tax Withholding

Check your paycheck or estimated tax payments to ensure you're not overpaying or underpaying. Adjusting whitholding before year-end can prevent surprises  come April. 

5. Take Advantage of Tax Credits

Maximize credits like the Child Tax Credit, Earned Income Tax Credit, or education-related credits. These directly reduce your tax bill rather than just your taxable income. 

6. Leverage the Gift Tax Exclusion

Consider using the annual gift tax exclusion ($18,000 per recipient in 2025) to shift wealth to family members without incurring gift taxes. Gifts can reduce the size of your taxable estate while helping loved ones financially. 

Example: Did you know that a married couple can give a married child and their spouse $72,000 in total? 

  • Mom gives daughter $18,000
  • Dad gives daughter $18,000
  • Mom gives son-in-law $18,000
  • Dad gives son-in-law $18,000

By splitting gifts this way, the couple fully uses the annual exclusion for each recipient without triggering gift taxes. 

7. Make Qualified Charitable Distributions (QCDs)

If you are 70½ or older, consider using a Qualified Charitable Distribution from your IRA. QCDs allow you to donate up to $108,000 directly to a qualified charity in 2025, counting toward your required minimum distribution (RMD) while excluding the donation from taxable income. This strategy can lower your adjusted gross income and potentially reduce Medicare premiums or tax on Social Security benefits

Year-end tax planning is about more than just checking boxes—it’s an opportunity to optimize savings, leverage credits, and strategically position your finances for the coming year. A review with a tax professional can ensure these strategies fit your situation and maximize your benefits. taxable income. This strategy can lower your adjusted gross income and potentially reduce Medicare premiums or tax on Social Security benefits.

This material and the opinions voiced are for general information only and are not intended to provide specific advice or recommendations for any individual or entity. To determine what is appropriate for you, please contact your Rose Street Financial Professional. Information obtained from third-party sources are believed to be reliable but not guaranteed.  The tax and legal references attached herein are provided with the understanding that neither M Financial Group, nor its Member Firms are engaged in rendering tax, legal, or actuarial services. If tax, legal, or actuarial advice is required, you should consult your accountant, attorney, or actuary. Neither M Financial Group, nor its Member Firms should replace those advisors.

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated.  File #4844566

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Interested in more?

Let's Talk Proactive HR

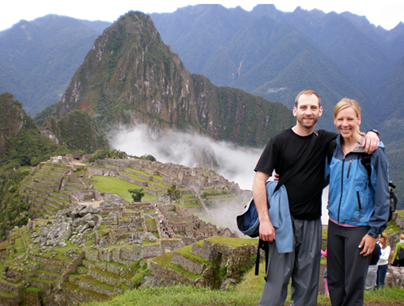
In the spring of 2008, my wife and I spent several days trekking through Peru’s Andes Mountains on our way to Machu Picchu. The climbs were steep, the air thin, and the scenery breathtaking. But what we remember most is the team of sherpas who turned a demanding expedition into an unforgettable journey—while staying completely out of the spotlight.

From the first morning, the sherpas set the pace and prepared us for each leg of the climb. They balanced heavy packs on donkeys, cooked full meals at 10–15,000 feet, and somehow managed to bake a surprise birthday cake for my wife halfway through the trip. Their skill with the tools of the trade—sturdy ropes, perfectly packed gear, and altitude-tested cooking equipment—kept us comfortable and safe while we focused on the views and the experience.

At every scenic overlook, they urged us to pause, breathe, and take in the beauty. Yet when it came time for photos at the summit, the sherpas quietly stepped behind the camera. They were happiest as the experts behind the scenes, making the journey possible while letting us enjoy the moment.

That trek mirrors how our wealth-management team serves clients. We realize how hard you have worked so hard to get to the point you have and why you are now seeking professional guidance.  We begin by understanding your goals and mapping the route.  We then take over and carry the load through this next lag of the journey—investment research, tax strategy, regularly trading to take advantage of the trends, keeping your portfolio wisely diversified,  estate planning—and we bring the right tools and partnerships so you can focus on life’s vistas. When markets shift or unexpected challenges arise, we adjust the path and keep you moving toward your destination.

Just as our sherpas found joy in seeing us reach the amazing view at the end, we find fulfillment in helping clients achieve their financial summits. The amazing view you have of seeing your kids and grandkids enjoy experiences you have worked so hard for and the celebrations are yours; we’re the steady, experienced guides working quietly in the background to make the climb safe, rewarding, and memorable.

This material and the opinions voiced are for general information only and are not intended to provide specific advice or recommendations for any individual or entity. To determine what is appropriate for you, please contact your Rose Street Financial Professional. Information obtained from third-party sources are believed to be reliable but not guaranteed.  The tax and legal references attached herein are provided with the understanding that neither M Financial Group, nor its Member Firms are engaged in rendering tax, legal, or actuarial services. If tax, legal, or actuarial advice is required, you should consult your accountant, attorney, or actuary. Neither M Financial Group, nor its Member Firms should replace those advisors.

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated.  File #4842476

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Interested in more?

Let's Talk Proactive HR

The Pre-Flight Checklist: Double Check Your Beneficiaries

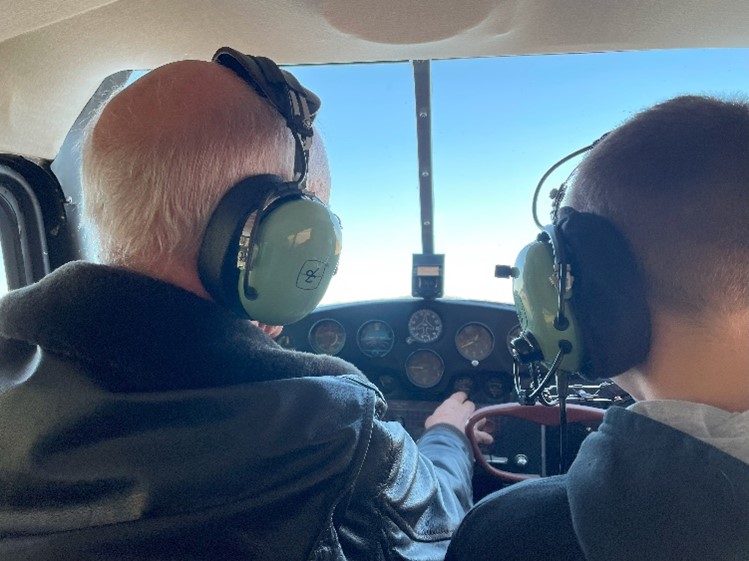
When we flew in Jim’s Cessna 170, we had no idea it would be the last time. For years, my son has shared his dream of becoming a pilot. Spending time with Jim and flying in his plane is a memory we will never forget. Jim was a passionate aviator and generously shared his love of flying with my son. Shortly after this flight, Jim was diagnosed with a terminal illness and passed away months later.

While we don’t often think about it, none of us know when our last flight will be. Just as pilots follow a strict pre-flight checklist before takeoff, there are important steps we encourage our clients to take to ensure their assets support the people and causes they care about most.

1. Verify Your Current Beneficiaries

Just as a pilot confirms fuel levels before takeoff, check that listed beneficiaries on your investment accounts are accurate. Life changes such as marriage, divorce, births, or deaths may require updates to reflect your current wishes. 

2. Confirm Accuracy of Information

A pilot checks all instruments before takeoff to avoid errors. Likewise, ensure that the names, contact details and Social Security numbers of your beneficiaries and are correct to prevent complications later.

3. Align Your Legacy with Your Passion

Before takeoff, a pilot sets their course. Consider whether your beneficiaries reflect your values and interests. Naming a non-profit organization that aligns with your passion will continue inspiring future generations and further your legacy.

Just as Jim's legacy lives on through his passion for aviation and the memories he created, we have the opportunity to leave our own legacy. Taking the time to review and update your beneficiaries ensures that your hard-earned assets are directed to the people and causes that matter most. It’s a simple yet powerful way to safeguard what’s important to you. Remember, life is unpredictable, and while we will never know last flight takes place, we can ensure our financial legacy is ready to take off when the time comes.

7642154.1This material and the opinions voiced are for general information only and are not intended to provide specific advice or recommendations for any individual or entity. To determine what is appropriate for you, please contact your Rose Street Financial Professional. Information obtained from third-party sources are believed to be reliable but not guaranteed.  The tax and legal references attached herein are provided with the understanding that neither M Financial Group, nor its Member Firms are engaged in rendering tax, legal, or actuarial services. If tax, legal, or actuarial advice is required, you should consult your accountant, attorney, or actuary. Neither M Financial Group, nor its Member Firms should replace those advisors.

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated.  File #7085279.1

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Jeremy is passionate about partnering with individuals and families to identify what is important in their lives and creating a comprehensive financial strategy to help them reach their life goals. This holistic approach allows Jeremy and the wealth management team to ensure the specific needs of the client are front and center as they make investment recommendations and collaboratively design custom-tailored financial plans.

Jeremy has a professional track record starting, leading, and managing for-profit and non-profit organizations.  He is a graduate of Taylor University and has completed business programs at both Hong Kong Baptist University & Harvard Business School.  Jeremy is also formally trained and certified in behavioral assessment, conflict management and life coaching.  Jeremy, his wife Kim and their 4 kids reside in Kalamazoo.  They love spending time exploring the outdoors, fixing up their farmhouse, and living life with friends and extended family.

Fun fact:  Jeremy has been playing drums since he was 13 years old and made callbacks for the Blue Man Group.

Interested in more?

Let's Talk Proactive HR

From Tax Savings to Lasting Impact: Making Giving a Family Affair

We have all heard, “lessons are better caught than taught.”  As a family, we have had fun including our kids in our goal to be a generous family.  From hosting people in our home to serving together in the community to finding ways to invest our money in people and causes we care deeply about; we have tried to do what we can to include our kids in the process.  While we are trying our best as parents to instruct our kids, the lessons that stick are often when they see something good or bad, in their parents.  Maybe you can relate! 

Many of our clients want to do more than invest their money in people and causes, they want to pass on the joy of giving to the next generation, too!  One of the fastest growing way to give is through a Donor-Advised Fund (DAF). It’s easy to set up, offers significant tax advantages, and—best of all—can involve your entire family in making a thoughtful, lasting impact.

What's a Donor-Advised Fund (DAF)?

A DAF is like a charitable investment account. You contribute cash, stocks, or other assets, receive an immediate tax deduction, and then recommend grants to nonprofits over time. The funds can grow tax-free while you plan your giving.

With today’s high standard deduction ($14,600 for individuals, $29,200 for married couples in 2025), many donors no longer itemize deductions annually. That’s where "bunching" comes in: You can contribute several years' worth of charitable giving to your DAF in a single year, itemize the deduction for that year, and then give gradually from that account over time, taking the standard deduction for years you won’t exceed the deduction limits by itemizing. This strategy provides a larger tax break without changing your actual giving goals.

How to Involve Your Family

1. Start the Conversation

Talk about why you give. Share a story or show your kids a video of a need and ask what causes they care about too.

2. Let Them Recommend Grants: 

Each family member can help direct a portion of the fund—making giving a shared and meaningful activity.

3. Pass the Torch

You can name your children or grandchildren as future advisors to your DAF, continuing your legacy of generosity.

A Legacy That Lives On

A DAF is more than a financial tool—it’s a bridge between wise planning and heartfelt impact. It allows you to give smarter, involve your family, and support great causes a sustainable, tax-wise way.  Want to learn more?  Let’s chat.

Jeremy Heavey| AIF ®, NSSA®

Financial Advisor 

Jeremy is passionate about partnering with individuals and families to identify what is important in their lives and creating a comprehensive financial strategy to help them reach their life goals. This holistic approach allows Jeremy and the wealth management team to ensure the specific needs of the client are front and center as they make investment recommendations and collaboratively design custom-tailored financial plans.

This material and the opinions voiced are for general information only and are not intended to provide specific advice or recommendations for any individual or entity. To determine what is appropriate for you, please contact your Rose Street Financial Professional. Information obtained from third-party sources are believed to be reliable but not guaranteed. The tax and legal references attached herein are provided with the understanding that neither M Financial Group, nor its Member Firms are engaged in rendering tax, legal, or actuarial services. If tax, legal, or actuarial advice is required, you should consult your accountant, attorney, or actuary. Neither M Financial Group, nor its Member Firms should replace those advisors.

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File # 4613023

When our oldest got her first job, we were thrilled for her!  As her parents, we were trying to balance being excited while helping her learn how to manage the bigger paychecks than she had seen in the past from babysitting and other odd jobs.  As your teen(s) start earning their own money, guiding them through a few key financial moves can set them up for future success. Here are a few ideas to get them started on the right track!

1. Help Them Set Up a Budget and Track Spending 

With that first paycheck comes the responsibility of managing money. Encourage them to create a budget that lists their income and expenses—think car expenses, cell phone bill, donations, college savings and of course, all those fun extras.  Just like us adults, a solid budget will help them keep tabs on where their money is going and make sure they’re living within their means. There are plenty of budgeting apps and tools out there that can make this task easier and even a bit enjoyable.

Budgeting tips to share:

•  Start with a basic budget or recommend a budgeting app.

•  Emphasize the importance of including savings in their budget so they get used to living on less than they make from the beginning.

•  Suggest reviewing and adjusting the budget regularly as their financial situation evolves.

2. Encourage Building an Emergency Fund 

As we know, life has a way of throwing unexpected expenses our way and it is important for them to start planning for unexpected expenses (or even opportunities like participating in a fun experience with their friends). Advise them to save up enough to cover three to six months of normal expenses in a separate savings account. This emergency fund will act as a financial safety net, helping them not always coming to their parents when those surprises come up.

How to build an emergency fund: 

•  Help them set a savings goal based on their monthly expenses.

•  Suggest setting up automatic transfers to their savings account each payday.

•  Remind them that even small, consistent deposits will grow over time.

3. Talk About Starting Retirement Savings 

It might seem far off, but starting to save for retirement now can make a huge difference later on financially and even mentally, teaching them the discipline to live on less than they make. As soon as your teen has an earned income and needs to file a tax return, they are now eligible to contribute to a Roth IRA.  Your teen can put up to the annual max, or their actual earned income, whichever is lower.  You (or a grandparent) could even offer a matching program!  For every dollar they put in, the parent puts in a dollar.  The earlier they start, the more they’ll benefit from compound interest.  Don’t forget, if needed, they can withdraw the basis (amount they contribute, not the growth) at any point without a penalty.

Retirement savings advice: 

•  Recommend opening and beginning to fund a Roth IRA.

•  If they have a company retirement plan that they are eligible for, encourage them to consider contributing enough to their 401(k) to get any

employer match.

•  Suggest aiming to invest around 10-15% of their income for retirement.

Wrapping Up

Helping your teen navigate their first job and their new financial responsibilities can make a big difference in setting them up for a successful future. By guiding them through budgeting, building an emergency fund and starting retirement savings, you’re giving them the tools they need to thrive financially. Your support and advice will help them tackle these early financial steps with confidence and prepare for a bright future ahead.

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #6968916.1

Jeremy Heavey

AIF ® | FINANCIAL ADVISOR

Jeremy is passionate about partnering with individuals and families to identify what is important in their lives and creating a comprehensive financial strategy to help them reach their life goals. This holistic approach allows Jeremy and the wealth management team to ensure the specific needs of the client are front and center as they make investment recommendations and collaboratively design custom-tailored financial plans.

Jeremy has a professional track record starting, leading, and managing for-profit and non-profit organizations.  He is a graduate of Taylor University and has completed business programs at both Hong Kong Baptist University & Harvard Business School.  Jeremy is also formally trained and certified in behavioral assessment, conflict management and life coaching.  Jeremy, his wife Kim and their 4 kids reside in Kalamazoo.  They love spending time exploring the outdoors, fixing up their farmhouse, and living life with friends and extended family.

Fun fact:  Jeremy has been playing drums since he was 13 years old and made callbacks for the Blue Man Group.

Interested in more?

Let's Talk Proactive HR

It is officially Summer!  Favorite summer past times of grilling burgers, hotdogs, swimming, boating, gardening, camping and just spending time outside is here.  A staple in many American refrigerators in the summertime, and throughout the year, is Ketchup.  Ketchup has a way of giving those grilling favorites that much needed edge to just simply make it better.  Just like ketchup gives our grilling favorites the edge needed, catch-up contributions in a 401k can serve the same purpose. 

If you or someone you love is still working and is or going to turn 50 this year, while the normal contribution limit to a 401k/403b plan is $23,000 for 2024, those 50 and older can make catch-up contributions of an additional $7,500, totaling $30,500.  The extra amount contributed can really give an investor’s portfolio the extra boost needed to stay on track or get back on track for retirement goals. 

On December 29, 2022, Congress passed the SECURE 2.0 Act, which stands for Setting Every Community Up for Retirement Enhancement.  Several of the provisions outlined in the act have delayed start dates.  Beginning in 2025, Section 109 of the SECURE 2.0 Act allows employees who are 60-63 years old to contribute at a “super” catch-up rate!  The super catch-up allows for investors to make an additional 50% increase to the $7,500, which would result in $11,250 in additional catch-up contributions in 2025.  This catch-up contribution is planned to index to inflation and could mean possibly more contributions in future years.

If you have questions or want to learn more, please reach out and let's chat.

 
Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File # 6718069.1

Jeremy Heavey

AIF ® | FINANCIAL ADVISOR

Jeremy is passionate about partnering with individuals and families to identify what is important in their lives and creating a comprehensive financial strategy to help them reach their life goals. This holistic approach allows Jeremy and the wealth management team to ensure the specific needs of the client are front and center as they make investment recommendations and collaboratively design custom-tailored financial plans.

Jeremy has a professional track record starting, leading, and managing for-profit and non-profit organizations.  He is a graduate of Taylor University and has completed business programs at both Hong Kong Baptist University & Harvard Business School.  Jeremy is also formally trained and certified in behavioral assessment, conflict management and life coaching.  Jeremy, his wife Kim and their 4 kids reside in Kalamazoo.  They love spending time exploring the outdoors, fixing up their farmhouse, and living life with friends and extended family.

Fun fact:  Jeremy has been playing drums since he was 13 years old and made callbacks for the Blue Man Group.

Interested in more?

Let's Talk Proactive HR
Are you looking for a Financial Advisor in Kalamazoo?  Finding the right financial advisor to partner with you and your family is crucial in helping you work towards your goals.  Whether you're planning for retirement, managing investments, seeking advice on holistic financial planning or all of the above, a skilled financial advisor is a critical part of your team.  As you are seeking to find the best financial advisor for YOU, consider these 5 tips:

1. Define Your Financial Goals

Before you start your search for a financial advisor, it's crucial to have a clear understanding of your financial goals and objectives. Are you looking for retirement planning, investment management, debt reduction strategies, or comprehensive financial planning or maybe some or all of the above? Knowing your specific needs will help you narrow down your search and find an advisor with expertise in the areas that matter most to you.

2. Learn How they Are Licensed

When considering potential financial advisors, it's essential to learn how they are licensed. There are 2 distinct ways to be licensed, as a fee-based fiduciary advisor or a commissioned-based broker.  Depending on your needs and desires, one might be a better fit than the other.  Look for advisors who hold reputable certifications such as Certified Financial Planners (CFP), Certified Financial Analysts (CFA) or Accredited Investment Fiduciaries (AIF). These designations require education, experience, and ethical standards, ensuring that your advisor has the necessary expertise to provide sound financial advice.

3. Seek Recommendations and Referrals

One of the most reliable ways to find a trustworthy financial advisor is through recommendations from friends, family, or colleagues who have had positive experiences. Ask people in your network if they can recommend an advisor they trust and/or ask your advisor if they can share some references you can contact. Additionally, you can consult with professionals in related fields, such as attorneys or accountants, who often work with financial advisors and may provide referrals.

4. Interview Potential Advisors

Once you've compiled a list of potential advisors, schedule initial interviews or consultations. Advisors who are serious about working with you will usually provide a complimentary consultation.  This is an opportunity to get to know the advisors and assess their compatibility with your financial goals and personal values. During these meetings, ask questions about their investment philosophy, fee structure, and client services. Pay attention to their communication style and willingness to listen to your concerns and objectives.

5. Understand Fee Structures

Financial advisors charge in various ways, including commissions, flat fees, hourly rates, or a percentage of assets under management. It's essential to understand how your potential advisor charges for their services and how this fee structure aligns with your financial situation, goals and preferences. Be transparent about your expectations to ensure there are no surprises down the road.

Choosing the right financial advisor in Kalamazoo is a significant decision that can have a lasting impact on your financial well-being. By defining your goals, checking qualifications, seeking recommendations, interviewing potential advisors, and understanding fee structures, you can make an informed choice that aligns with your financial objectives. Remember that trust, compatibility, and open communication are key factors in building a successful advisor-client relationship. 

At Rose Street Advisors, we often tell our clients and potential clients that the more we know about them, the better we can put together a tax-efficient holistic financial life plan, build and manage a diversified portfolio and serve as their personal CFO, helping guide them towards their goals.  Want to know more?  We are always happy to have a chat.

 
Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File # 6439955.1

Jeremy Heavey

AIF ® | FINANCIAL ADVISOR

Jeremy is passionate about partnering with individuals and families to identify what is important in their lives and creating a comprehensive financial strategy to help them reach their life goals. This holistic approach allows Jeremy and the wealth management team to ensure the specific needs of the client are front and center as they make investment recommendations and collaboratively design custom-tailored financial plans. Jeremy has a professional track record starting, leading, and managing for-profit and non-profit organizations.  He is a graduate of Taylor University and has completed business programs at both Hong Kong Baptist University & Harvard Business School.  Jeremy is also formally trained and certified in behavioral assessment, conflict management and life coaching.  Jeremy, his wife Kim and their 4 kids reside in Kalamazoo.  They love spending time exploring the outdoors, fixing up their farmhouse, and living life with friends and extended family. Fun fact:  Jeremy has been playing drums since he was 13 years old and made callbacks for the Blue Man Group.

Interested in more?

Let's Talk Proactive HR

Less Tax for You.  More Money to the Charity.  Nothing for the Government.  What’s not to love?

When you reach 73 years old, you are required to start taking minimum distributions from your traditional IRAs and certain other retirement accounts. These distributions are generally subject to income tax. If you are charitably inclined, you may be able to satisfy all or a portion of your required minimum distribution, lower your taxable income and give more to the charity by utilizing a special provision called a Qualified Charitable Distribution (QCD).  A QCD allows you to donate funds directly from your traditional Individual Retirement Accounts (IRAs) to eligible charitable organizations. The donated amount counts towards your Required Minimum Distribution (RMD) for the year AND is excluded from your taxable income.  This can result in a lower overall tax liability for you and potentially more money going directly to the charity.

As you seek ways to help to optimize your financial situation while making meaningful contributions to society, QCDs provide a versatile tool to achieve both objectives. Before making any decisions, it's important to consult with a professional advisor who can help tailor this strategy to your specific circumstances and charitable goals. With proper planning, QCDs can serve as a win-win solution for retirees and the charitable organizations you support.


Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File # 5922845.1

Jeremy Heavey

AIF ® | FINANCIAL ADVISOR

Jeremy is passionate about partnering with individuals and families to identify what is important in their lives and creating a comprehensive financial strategy to help them reach their life goals. This holistic approach allows Jeremy and the wealth management team to ensure the specific needs of the client are front and center as they make investment recommendations and collaboratively design custom-tailored financial plans.

Jeremy has a professional track record starting, leading, and managing for-profit and non-profit organizations.  He is a graduate of Taylor University and has completed business programs at both Hong Kong Baptist University & Harvard Business School.  Jeremy is also formally trained and certified in behavioral assessment, conflict management and life coaching.  Jeremy, his wife Kim and their 4 kids reside in Kalamazoo.  They love spending time exploring the outdoors, fixing up their farmhouse, and living life with friends and extended family.

Fun fact:  Jeremy has been playing drums since he was 13 years old and made callbacks for the Blue Man Group.

Interested in more?

Let's Talk Proactive HR
A few years ago, I bought a smoker to smoke meat.  If you have ever smoked meat, you know that it takes a LONG time to cook, but it is SO worth it!  And because it takes so long, we typically smoke more meat than we need to so there are leftovers for days to come.  The leftover smoked meat makes incredible chili, tasty omelets, sandwiches and who knows what!  As a busy family with 4 kids, really good food that is leftover isn’t leftover for long!  If you have kids that are considering college, you have probably thought about ways to pay for it.  A popular option, for good reason, is a 529 Plan. A 529 is a tax favored account for education that grows tax-free and is not ever subject to tax if used for eligible education expenses. 529 Plans are state-specific, with each state having its own rules and limits*. But that is for another article!  For many of our clients, they have invested some money in a 529 plan but find themselves wondering – what happens if my kid doesn’t go to college, or we don’t spend all of it?  What do we do with the leftovers?

1.) Child's post-graduate education.

Most 529 plans allow this, so it's a great way to continue saving for your child's future education.

2.) Transfer the funds to another beneficiary.

This can be another child, grandchild, or even yourself if you decide to go back to school. As long as the new beneficiary is a qualified family member (spouse, son, daughter, son-in-law, daughter-in-law, niece, nephew, or their spouse, etc), you can use the funds for their education.

3.) Allocate up to $10k to be used for K-12 education expenses.

A new law in 2018 allows for private school tuition, books, and other related expenses to be paid with the leftover funds.

4.) Other education options.

Such as vocational schools, trade schools, and apprenticeships.

5.) Roll up to $35k* (lifetime limit per beneficiary) into a Roth IRA.

Beginning 2024 for the benefit of the student (not the parent or grandparent who funded the account).  *there has been some information released (in the SECURE Act 2.) at the end of December 2022) on the age of the 529 plan account, limits, etc but we are still waiting on some clarification from the Government on specifics.

6.) Withdraw the funds.

But be aware that if you use the funds for non-qualified expenses, you will have to pay taxes on the earnings and a 10% penalty. So, it's important to consider all other options before withdrawing the funds. There are several options for what to do with leftover funds in your 529 plan. Sometimes having leftovers is a great problem to have!  If you have questions, let’s chat…over lunch at a BBQ place! *Before investing, the investor should consider whether the investor or beneficiary’s home state offers any state tax or other benefits available only from that state’s 529 Plan.
Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File # 5646225.1

Jeremy Heavey

AIF ® | FINANCIAL ADVISOR

Jeremy is passionate about partnering with individuals and families to identify what is important in their lives and creating a comprehensive financial strategy to help them reach their life goals. This holistic approach allows Jeremy and the wealth management team to ensure the specific needs of the client are front and center as they make investment recommendations and collaboratively design custom-tailored financial plans. Jeremy has a professional track record starting, leading, and managing for-profit and non-profit organizations.  He is a graduate of Taylor University and has completed business programs at both Hong Kong Baptist University & Harvard Business School.  Jeremy is also formally trained and certified in behavioral assessment, conflict management and life coaching.  Jeremy, his wife Kim and their 4 kids reside in Kalamazoo.  They love spending time exploring the outdoors, fixing up their farmhouse, and living life with friends and extended family. Fun fact:  Jeremy has been playing drums since he was 13 years old and made callbacks for the Blue Man Group.

Interested in more?

Let's Talk Proactive HR
« Previous Page
Next Page »
Rose Street Advisors

Your guide from hire to retire. Rose Street Advisors provides the strategy companies need to grow with confidence.

Firm
About UsOur TeamCommunity SupportTestimonials
Services
Employee BenefitsHR ConsultingLife InsuranceEmployer Retirement PlansWealth ManagementFiduciary Fitness
Contact

244 North Rose Street
Kalamazoo, MI 49007

5181 Plainfield Ave NE
Grand Rapids, MI 49525

269.552.3200
© 2026 Rose Street Advisors LLC. All rights reserved.
Securities and Investment Advisory Services Offered Through M Holdings Securities, Inc. A Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors is independently owned and operated. Please go to www.mfin.com/DisclosureStatement for further details regarding this relationship. Check the background of this Firm and/or investment professional on FINRA's BrokerCheck. For important information related to M Securities, refer to the M Securities' Client Relationship Summary (Form CRS) by navigating to mfin.com/m-securities. Registered Representatives are registered to conduct securities business and licensed to conduct insurance business in limited states. Response to, or contact with, residents of other states will only be made upon compliance with applicable licensing and registration requirements. The information in this website is for U.S. residents only and does not constitute an offer to sell, or a solicitation of an offer to purchase brokerage services to persons outside of the United States. This site is for information purposes and should not be construed as legal or tax advice and is not intended to replace the advice of a qualified attorney, financial or tax advisor or plan provider. CA Insurance License. File #5757992.1

We value your privacy

We use cookies to keep this site reliable, understand how it’s used, and — with your permission — to personalize content. You can accept all, reject non-essential, or choose which categories to allow.

Privacy Policy

Cookie Preferences