Rose Street Advisors Rose Street Advisors
Firm
About UsOur TeamM Financial GroupEducation LibraryCommunity SupportTestimonials
Benefits
Employee Benefit ServicesBenefits FAQBenefits University Blog
HR Consulting
HR Consulting ServicesHR BlogRose Street Recruits
Life Insurance
Life Insurance ServicesLife Happens BlogLife Insurance Vlog
Employer Retirement Plans
Retirement ServicesFiduciary Fitness ProgramGuide to Retirement BlogRetirement Plans FAQ
Wealth Management
Wealth Management ServicesInvestED BlogWealth Management FAQs
Get In Touch

At Rose Street Advisors, we help retirees evaluate and execute Roth conversions every year. For many clients, a Roth conversion can be an important part of a thoughtful retirement and tax strategy.  But we've also learned something important:

Just because you can do a Roth conversion doesn't mean you should.

The right question isn't how much you can convert. It's whether converting makes sense for your specific situation.  Here are five situations where retirees should think twice.

  1. 1. You Don't Have Heirs Who Will Benefit

One of the biggest potential benefits of a Roth is leaving tax-free assets to your heirs.

But what if you don't plan to leave significant assets to children or other beneficiaries?  If your goal is to spend your retirement assets during your lifetime, paying taxes today to create a tax-free inheritance may provide little benefit.

There may still be reasons to convert, such as reducing future RMDs or managing future taxable income. But the conversion should have a clear purpose.

If nobody is going to benefit from the Roth later, ask why you're paying the tax today.

  1. 2. You're Planning to Give the Money to Charity

Retirement accounts can be valuable charitable assets.

If you plan to leave a significant portion of your IRA to charity, converting those dollars to a Roth first may mean paying taxes on money that could potentially pass directly to a qualified charity without creating the same income-tax burden.  The better question may not be, "How much should I convert?"

It may be, "Which assets should go to charity and which should go to my family?"

Sometimes the best Roth conversion is the one you don't make.

  1. 3. You Don't Have Cash to Pay the Taxes

A Roth conversion creates taxable income.  If you convert $200,000 and owe $50,000 in federal and state taxes, where will that $50,000 come from?  Ideally, you pay the tax with money outside the IRA. Otherwise, you may have to use part of the retirement account to pay the tax, reducing the amount that actually makes it into the Roth.

Before converting, make sure you have a plan for the tax bill.

  1. 4. The Conversion Will Increase Your Medicare Premiums

For retirees on Medicare, don't forget about IRMAA, the Income-Related Monthly Adjustment Amount. A Roth conversion can increase your income enough to trigger higher Medicare Part B and Part D premiums.  And there's a two-year lookback.

For example, a conversion in 2026 can affect your Medicare premiums in 2028.  But here's the important point: paying additional IRMAA isn't necessarily a mistake.

If a larger Roth conversion meaningfully reduces future RMDs, creates more tax-free assets for heirs, or provides other long-term benefits, paying higher Medicare premiums for a year or two may be a reasonable tradeoff.  The mistake is ignoring IRMAA when doing the math.

  1. 5. You May Be in a Lower Tax Bracket Later

A Roth conversion means paying taxes today in exchange for potentially avoiding taxes later.  So what will your tax bracket look like in the future?  If your income is unusually high today but is expected to fall in future years, a large conversion may not make sense right now.

This is why Roth conversion planning should often be viewed as a multiyear strategy, not a one-time decision.  You may convert some this year, more next year, and less the year after.

The Bigger Question

The question isn't: "Should I do a Roth conversion?" It's:

"Does paying the tax today create enough value to justify the cost?"

That requires looking at taxes, RMDs, Medicare premiums, charitable intentions, estate plans, and how you actually intend to use your money.

At Rose Street Advisors, we use state-of-the-art planning technology to model these decisions and help clients see the potential tax impact of different Roth conversion strategies before making a decision.

Sometimes the answer is to convert.  Sometimes the answer is to wait.  And sometimes the answer is don't convert at all.

Don't convert just because you can. Convert because it serves a purpose.

Good retirement planning isn't about finding the latest strategy and checking a box.

It's about making sure every financial decision has a purpose.

If you're wondering whether a Roth conversion makes sense for your retirement plan, contact Rose Street Advisors.We'd be happy to help you evaluate the numbers, the tradeoffs, and the potential long-term impact of a conversion.

Contact us to see whether a Roth conversion is right for you.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5943979

Interested in more?

Let's Talk Proactive HR

If your parent is still alive but the end may be near, we recommend reading our article "What To Do When the End Is Near." That guide walks through important conversations, documents, and financial steps that can make everything that follows much smoother. Preparing ahead of time can reduce stress, prevent delays, and help families move forward with greater clarity.

When your last parent passes away, you’re not just grieving. You’re stepping into a new role. You’re now the next generation. The one responsible for decisions, communication, and organization.

That can feel overwhelming. This guide is designed so someone could sit at a kitchen table and simply start working through it.

Before the checklist, one of the most helpful things to understand is timeline. Many families feel pressure to wrap things up quickly. In reality, settling an estate takes time, and that is completely normal.

A Realistic Timeline (So You Can Set Expectations)

First 1–2 weeks Order death certificates Secure home and assets Locate documents Notify financial advisor Begin gathering account information

Weeks 3–4 Contact attorney if probate may be needed Determine beneficiaries Create initial asset list Confirm executor or trustee Continue notifications

2–6 months Open estate if needed Pay bills and expenses Collect insurance proceeds Transfer accounts Prepare home for sale if applicable Complete required distributions

6–12 months (sometimes longer) File final tax return Resolve outstanding issues Distribute remaining assets Close estate

Important note to communicate to heirs

It is wise not to distribute money immediately. Taxes, expenses, and unknowns can arise. Moving slowly protects everyone and avoids asking for money back later.

You can say

"We are working through everything carefully. Most estates take several months to settle. We want to make sure taxes, expenses, and paperwork are handled correctly before distributions."

  1. 1. Slow Down Before Making Major Decisions

This is not the time to sell the house, move money, or divide assets. Grief impacts judgment. Very few financial decisions are urgent, but many mistakes happen when people move too quickly.

Pause. Gather information. Communicate. Then decide.

According to Cerulli Associates, $84 trillion is expected to transfer from older generations to heirs over the next two decades. These decisions are often large. Taking time matters.

  1. 2. Order Death Certificates

You will likely need death certificates, but fewer organizations require original copies today than in the past.

Ordering 5 to 8 copies is typically sufficient. In many cases, scanned copies are accepted. The most common situations requiring original death certificates include transferring real estate through the Register of Deeds and the occasional financial institution.

Where to order
• Funeral home (easiest)
• County clerk
• State vital records office


Immediately after receiving them Create a high-quality digital scan. Many organizations accept digital copies.

Checklist
☐ Order multiple copies (5–8 typically sufficient)
☐ Create digital scan
☐ Store originals safely


  1. 3. Secure the Home and Immediate Assets

This protects against theft, damage, and insurance issues.

Checklist
☐ Lock home
☐ Confirm homeowners insurance active
☐ Forward mail
☐ Maintain utilities
☐ Care for pets or dependents
☐ Remove obvious valuables if needed


  1. 4. Notify Key Organizations

This stops payments, prevents fraud, and starts transitions.

In many cases, the funeral home notifies Social Security, which then flows through to Medicare and Medicaid. Because of this, families often do not need to contact these agencies directly. However, it is still wise to confirm benefits have stopped appropriately.

What to say when calling

"I'm calling to report the death of [Name]. They passed away on [date]. I'm [relationship]. What do you need from me and what are the next steps?"

They may ask for
• Name
• Date of death
• Social Security number
• Death certificate
• Your contact information


Notify these first

Financial
☐ Banks
☐ Investment firms
☐ Retirement accounts
☐ Pension providers


Insurance
☐ Life insurance
☐ Homeowners insurance
☐ Auto insurance


Professional contacts
☐ Financial advisor
☐ CPA
☐ Attorney


Employer if applicable
Ask about
• Final paycheck
• Pension
• 401(k)v • Life insurance


How to Notify Credit Bureaus (Identity Theft Protection)

Experian 888-397-3742

Equifax 888-548-7878

TransUnion 800-680-7289

What they need
• Name
• Social Security number
• Date of death
• Death certificate


Ask them to
• Flag file as deceased
• Send credit report
• Block new credit


Important tip Ask each organization what they need. Some require originals, others accept digital copies.

  1. 5. Contact the Financial Advisor

This is one of the most important early calls. You do not need multiple calls. Ask them to gather everything.

Tell them

"My parent passed away. Can you help me gather everything and outline next steps?"

  • Ask them to provide List of all accounts
    • Beneficiaries on each account
    • Date-of-death values
    • Step-up in cost basis values
    • Required distributions
    • Life Insurance Policies
  • What paperwork is needed Which assets avoid probate
    • Estimated timeline

Checklist
☐ Notify advisor of death
☐ Request full asset list
☐ Request beneficiaries
☐ Request date-of-death values
☐ Ask about required distribution
☐ Ask what paperwork is needed


  1. 6. Gather Important Documents

Checklist
☐ Will or trust
☐ Account statements
☐ Life insurance policies
☐ Property deeds
☐ Tax returns
☐ Mortgage information


Where to look:
File cabinets
Safe deposit box
Attorney
Financial advisor
CPA
Mail
Email


Additional place many families overlook For older estates, the original will may be held at the probate court in the county where your parent lived. Decades ago, safekeeping wills at the court was common practice. While this is no longer standard, it is still worth checking, especially if documents cannot be located.

Executor or Trustee This is the person responsible for handling everything. They gather assets, pay bills, and distribute money according to the will or trust.

  1. 7. Determine if Probate or an Estate is Needed

What is probate Probate is the legal process that gives someone authority to act on behalf of the deceased. The court formally appoints the executor.

You may need probate if Assets in one name only No beneficiary listed No trust exists

You may NOT need probate if Assets in trust Beneficiary designations Joint ownership

Timing matters It often takes three to four weeks or longer for the court to open probate and issue Letters of Authority. Delays in starting this process can push back creditor notice periods and slow the overall timeline. If probate is likely, contacting an attorney within the first three to four weeks is typically helpful.

Opening an estate means Creating a legal entity called "The Estate of [Name]" so money can be collected and bills paid.

This often includes Court appointment if needed Opening estate checking account Depositing incoming funds Paying expenses

Checklist
☐ Determine if probate required
☐ Contact attorney within 3–4 weeks if needed
☐ File will with court if needed
☐ Receive executor authority
☐ Open estate checking account
☐ Pay bills from estate account
☐ Track expenses


  1. 8. Create a List of Assets and Debts

Checklist
☐ Bank accounts
☐ Investment accounts
☐ Retirement accounts
☐ Life insurance
☐ Real estate
☐ Vehicles
☐ Personal property
☐ Debts
☐ Mortgage
☐ Credit cards
☐ Medical bills


  1. 9. Understand Step-Up in Cost Basis and Handle Tax Valuations

One of the most important financial opportunities after a parent passes away is something called a step-up in cost basis. This can significantly reduce taxes for heirs.

What is step-up in cost basis When someone inherits investments or property, the value resets to the date-of-death value, not what the parent originally paid.

Capital gains tax is based on the difference between sale price and cost basis. The step-up eliminates taxes on gains that happened during your parent’s lifetime.

Example with investments

Your parent bought a stock for $20,000 At death, it is worth $100,000 You sell for $102,000

Without step-up Taxable gain = $82,000

With step-up Taxable gain = $2,000

Example with real estate

Parent bought home for $150,000 Value at death $400,000 You sell for $410,000

Without step-up Gain = $260,000

With step-up Gain = $10,000

Who provides values

Investments Your financial advisor typically provides
• Date of death values
• Cost basis reset
• Documentation


Ask them on the first call.

Real estate You can determine value using
• Real estate agent comparative market analysis
• Appraisal
• County tax value
• Online estimates as temporary reference


Checklist
☐ Request date-of-death values from advisor
☐ Confirm step-up applied
☐ Obtain real estate value
☐ Document values
☐ Avoid selling before confirmed
☐ Coordinate with tax preparer
☐ File final income tax return


  1. 10. Don’t Distribute Money Too Quickly

There may still be Taxes Bills Legal costs Unknown expenses

Checklist
☐ Identify expenses
☐ Set aside reserves
☐ Communicate timeline to heirs
☐ Distribute when clear


Where to Start First

☐ Order death certificates
☐ Secure home
☐ Notify financial advisor
☐ Contact attorney (if probate likely)
☐ Notify banks and institutions
☐ Gather documents
☐ Determine executor
☐ Create asset list


You do not need to do everything today. You just need to begin.

About Rose Street Advisors Wealth Management

At Rose Street Advisors Wealth Management, we work closely with individuals and families navigating life’s biggest financial transitions. Losing a parent and settling an estate is not just a financial process. It is emotional, relational, and often filled with decisions most people have never had to make before.

Our role is to bring clarity and calm to complex situations. We help families organize accounts, understand beneficiaries, coordinate with attorneys and tax professionals, determine step-up in cost basis values, and create a thoughtful timeline for distributions. Just as importantly, we help families avoid rushed decisions that can create unnecessary taxes or tension.

We often serve as a central point of coordination, helping ensure nothing is missed while allowing families to move at a thoughtful pace.

If you are walking through this process, you do not have to do it alone. We would be honored to help you think through next steps, answer questions, or simply provide guidance during a difficult season.

Please reach out to our team. We would be glad to help.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5350468

Interested in more?

Let's Talk Proactive HR

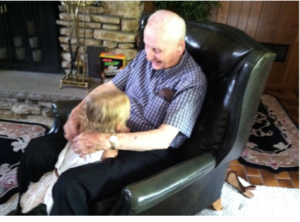
The pic is a little blury, but one that we will never get rid of.  We knew the end with my Grandpa was near, but didn’t know how near.  This was the last picture we have of my Grandpa and my oldest.  The look on his face tells the story.  He loved this moment!  He was an incredible man of faith, lover of kids and quiet powerhouse of a leader.  He led by serving people.  What a joy to have my daughter get a chance to spend a couple years with him before he passed away.  He and my Grandma were married for 66 years and led a life serving others.  They died within 8 months of each other.  What a legacy they built and left.

When a parent’s health is declining and the end may be near, families often feel two things at the same time. Emotionally, you want to be present. Practically, you know there are things that should be handled. This guide is meant to help you do both. You do not need to do everything at once.  You just need to start.

1. Have the Most Important Conversation

If your parent is able, this is the most valuable step.

Discuss
• Who makes medical decisions
• Who handles finances
• Care preferences (hospice, hospital, life support)
• Funeral wishes
• Where documents are located
• How assets should be handled
• Who communicates with family

Checklist
☐ Identify medical decision maker
☐ Identify financial decision maker
☐ Discuss care preferences
☐ Discuss funeral wishes
☐ Ask where documents are located

  1. Confirm Legal Documents

These allow you to act before death, not just after.

Important documents
• Will or trust
• Financial power of attorney
• Healthcare power of attorney
• Living will / advance directive
• HIPAA authorization
• Beneficiary designations

Double check life insurance beneficiaries. These override a will and are often outdated.

Checklist
☐ Locate will or trust
☐ Confirm financial POA
☐ Confirm healthcare POA
☐ Confirm advance directive
☐ Review retirement beneficiaries
☐ Review life insurance beneficiaries

  1. Identify Decision Makers

You should know:
• Medical decision maker
• Financial decision maker
• Executor
• Family communicator

Checklist
☐ Identify roles
☐ Share roles with family

  1. Gather Financial Information

You are simply identifying what exists.

Include
• Bank accounts
• Investment accounts
• Retirement accounts
• Life insurance
• Annuities
• Real estate
• Debts

Checklist
☐ List accounts
☐ List insurance
☐ List debts
☐ Gather statements

  1. Contact the Financial Advisor

They can help organize everything and prepare for what comes next.

They help with
• Account list
• Beneficiaries
• Life insurance review
• What avoids probate
• Liquidity needs
• Next steps

Checklist
☐ Notify advisor
☐ Request account list
☐ Confirm beneficiaries
☐ Double check life insurance beneficiaries
☐ Ask what to prepare now

  1. Understand What Transfers Automatically

Some assets transfer immediately
• Life insurance with beneficiary
• Retirement accounts with beneficiary
• Joint accounts
• Trust assets

Others may require probate
• Assets in one name
• No beneficiary
• No trust

Checklist
☐ Identify beneficiary accounts
☐ Identify probate assets

  1. Discuss the Home

This is often the largest decision.

Discuss
• Keep or sell
• Who maintains it
• Where documents are
• Mortgage and insurance

Checklist
☐ Discuss home plan
☐ Locate deed
☐ Confirm insurance

  1. Discuss Funeral Preferences

Consider
• Burial or cremation
• Funeral home
• Service preferences
• Cemetery
• Obituary

Checklist
☐ Burial vs cremation
☐ Funeral home
☐ Service preferences

  1. Determine How Expenses Will Be Paid

This prevents stress immediately after death.

Identify
• Life insurance
• Prepaid funeral plans
• Liquid accounts
• Who pays upfront expenses

Checklist
☐ Identify life insurance
☐ Confirm beneficiaries
☐ Identify liquid fund
☐ Determine who pays upfront

  1. Gather Digital Access

Often overlooked but extremely helpful.

Include
• Phone passcode
• Email access
• Financial logins
• Subscriptions
• Social media

Checklist
☐ Document phone access
☐ Document email access
☐ Document financial logins

  1. Create a Simple Information Sheet

Include
• Full name
• Social Security number
• Date of birth
• Advisor contact
• Attorney contact
• Account list
• Document locations

Checklist
☐ Create information sheet
☐ Share with trusted person

  1. Share Document Locations

Make sure the right people know where everything is.

Checklist
☐ Share document locations
☐ Provide copies to decision makers
☐ Confirm safe deposit box access

Where to Start First

☐ Have the conversation
☐ Identify decision makers
☐ Locate will and documents
☐ Double check life insurance beneficiaries
☐ Contact financial advisor
☐ List accounts
☐ Discuss funeral wishes
☐ Determine expense funding

You do not need to do everything today. You just need to begin.

About Rose Street Advisors Wealth Management

At Rose Street Advisors Wealth Management, we often walk alongside families during life’s most difficult transitions. When a parent’s health is declining, decisions become both emotional and practical. Many families are unsure what should be handled now versus later.

Our role is to bring clarity and calm during an uncertain time. We help families organize accounts, review beneficiaries, coordinate with attorneys, identify what will transfer smoothly, and prepare for the decisions that follow. Just as importantly, we help families avoid rushed decisions and focus on what matters most.

Planning ahead does not make this season easier emotionally, but it can remove uncertainty and reduce stress for everyone involved.

If your family is navigating this stage, we would be honored to help you think through next steps, answer questions, or simply provide guidance.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5350478

Interested in more?

Let's Talk Proactive HR

When most people think about financial planning, they picture investments, returns, or picking the “right” funds in their retirement plan.

But meaningful financial progress doesn’t start there.

It starts with you; your values, your goals, and what truly matters in your life.

Financial life planning is not about chasing performance. It’s about building a thoughtful, coordinated process that aligns every part of your financial life with the life you want to live.

  1. 1. Start With What Matters Most

Before any numbers or strategies come into play, take a step back and reflect:

  • What does a fulfilling life look like to me?
  • What are my top priorities. Now and in the future?
  • What does retirement mean beyond just “not working”?

For some, it’s freedom and flexibility. For others, it’s security, family, or the ability to give back.

Your financial plan should reflect these answers. Not someone else’s definition of success.

Clarity here drives every decision that follows.

  1. 2. Build Around Your Goals. Not Just Your Accounts

Once your priorities are clear, your financial strategy should begin to take shape. This is where a true planning process comes into focus.

It’s not just about your workplace retirement plan.   It’s about how all the pieces of your financial life work together, including:

  • Retirement income planning – How your savings turn into a reliable paycheck in retirement
  • Asset location – Placing investments in the right types of accounts (tax-deferred, Roth, taxable)
  • Tax planning – Being thoughtful about how and when income is recognized
  • Insurance planning – Protecting against risks that could derail your progress
  • Estate and legal planning – Ensuring your wishes are carried out and your family is supported

Each of these areas plays a role. When coordinated well, they create a more complete and resilient plan.

  1. 3. Focus on What You Can Control

A disciplined approach emphasizes the factors you can actually influence:

  • Saving consistently
  • Keeping costs low
  • Maintaining appropriate diversification
  • Staying invested through market cycles

Markets will move and sometimes unpredictably. A sound plan doesn’t try to outguess those movements. Instead, it’s built to endure them.

This is where process matters more than prediction.

  1. 4. Invest With Purpose

Your investment strategy should reflect your goals, time horizon, and comfort with risk. Not short-term headlines.

That means:

  • Avoiding emotional decisions during market volatility
  • Maintaining a diversified portfolio aligned with your plan
  • Understanding that risk and return are connected

The goal isn’t to eliminate risk, it’s to take the right amount of risk for your situation so you can stay on track.

  1. 5. Revisit and Adjust Over Time

Life changes and your plan should, too.

As your career evolves, your family grows, or retirement gets closer, your priorities may shift. Regular check-ins help ensure your strategy continues to align with what matters most.

Think of financial planning as an ongoing relationship with your future and not a one-time event.

A Real-Life Example

Consider Laura, a 42-year-old employee participating in her company’s retirement plan.

At first, Laura focused only on her 401(k), contributing enough to get the match and choosing a few funds she felt comfortable with. But she wasn’t sure if she was truly on track.

When she stepped back and went through a financial life planning process, a few important things became clear:

  • Her top priority wasn’t early retirement. It was flexibility in her late 50s to scale back work and spend more time with family.
  • She realized most of her savings were in pre-tax accounts, so she began adding Roth contributions to improve future tax flexibility.
  • She updated her beneficiaries and estate documents, something she hadn’t revisited in years.
  • She reviewed her insurance coverage to ensure her family would be protected if something unexpected happened.
  • And importantly, she began thinking about how her savings would translate into retirement income, not just an account balance.

Nothing about Laura’s situation required a drastic change. Instead, small, thoughtful adjustments, aligned with what mattered most to her, helped create a clearer, more confident path forward.

Bringing It All Together

Financial life planning is about connecting the dots.

It’s aligning your:

  • Goals
  • Investments
  • Income
  • Taxes
  • Protection strategies
  • Legacy wishes

…into one cohesive plan designed around you.

When each piece is working together, decisions become clearer and more intentional.

Final Thought

You don’t need to have everything figured out today.

Start with what matters most. Build a process around it. Stay consistent.

Over time, those thoughtful decisions can turn into something much more meaningful than just financial progress.  They can support a life that truly reflects who you are and what you value.

Scott Higgins | AIF ®, CFP®, CPFA®, NSSA®

Financial Advisor

Securities and Investment Advisory Services Offered Through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Adviser, Member FINRA/SIPC. Rose Street Advisors is independently owned and operated. #5653321

Interested in more?

Let's Talk Proactive HR

When meeting with our philanthropically minded clients, we often say, “give cash last.”  Donating cash is simple, but it’s not always the most tax efficient.  As we are nearing the end of the year, many clients plan to make charitable contributions, and it is our job to help make those contributions go as far as possible.  What does this mean for you?  If you have an IRA, investments like stocks or real estate that have appreciated over time, you might be better off donating those instead of cash. Why? Because by donating non-cash assets, you can often avoid capital gains taxes and/or income taxes. In other words, you’ll give more to charity without having to hand over extra cash to the government.  Here are the top 6 ways to get the biggest tax break for your donation:

1. Use Your IRA for Charitable Giving

Do you need to satisfy your Required Minimum Distributions (RMDs) from your IRA?   You can avoid the tax hit from those RMDs by donating directly from your IRA to charity through a Qualified Charitable Distribution (QCD).  Even if you are just 70 ½ and don’t have to take an RMD yet, you still maybe be eligible to give through a QCD.

How It Works:

• Contact your IRA provider and request a direct transfer to a qualified charity (or request a checkbook and write checks to charities yourself!

• The amount you give won’t be counted as taxable income, and it will satisfy your RMD.

Why It’s Smart: It’s a great way to reduce your taxable income while meeting your RMD requirement. It’s especially useful if you don’t need the income from your IRA for living expenses but still want to make a charitable impact.

2. Donate Appreciated Stocks, Bonds, or Mutual Funds

If you’ve got stocks, bonds, etfs or mutual funds in a taxable brokerage account that have increased in value since you bought them, this is one of the best ways to donate. Why?  When you donate these assets directly to a charity, you avoid paying capital gains taxes on the appreciation, and you get a tax deduction for the full market value of the securities.

How It Works:

• Look through your portfolio for any investments that have appreciated.

• Transfer the stocks, bonds, or funds directly to the charity (don’t sell them first).

• The charity then sells the investments tax-free and gets the proceeds to use for their cause.

Why It’s Smart: You avoid paying capital gains tax, so the value of your donation is higher. It’s a win-win—you give more, you get a tax break and the charity gets more.

3. Use a Donor-Advised Fund (DAF)

If you’re looking for flexibility, a donor-advised fund might be the perfect solution.

A DAF allows you to contribute cash or assets like stocks to an account, receive an immediate tax deduction, and then distribute the funds to charities over time. Think of it as your personal charitable giving account that you control. 

Donor Advised Funds are the fastest growing way to donate in the United States.  Because the standard deduction has been much higher in recent years, to get the biggest tax benefit, some investors are ‘bunching’ several years of giving into one tax year, getting the bigger tax benefit in that year, and then making distributions over the next several years. Think of giving more in a 2 year cycle that keeps repeating vs just giving directly from cash each year. 

For example, a donor might contribute $50k in one calendar year, receive the tax break for that year, and then make $25k worth of distributions in that year & another $25k worth of distributions in the next year, then load up the donor advised fund once again for another 2 year cycle.  This allows the donor to take the higher deduction in the year they are “bunching” their donations and the standard deduction in the “off years.”

How It Works:

• Set up a DAF through a sponsoring organization (most major financial institutions offer them).

• Donate assets like stocks or cash to the DAF.

• You get a tax deduction right away and then you can distribute grants to your favorite charities whenever you like.

Why It’s Smart: DAFs give you the freedom to plan your giving. You can invest the assets within the fund and let them grow, potentially increasing the amount you can eventually donate.

4. Give Tangible Personal Property (Art, Collectibles, etc.)

If you own valuable personal items like artwork, real estate, cars, or collectibles, these can also be donated to charity. Depending on the item and how it’s used by the charity, you may be able to deduct either the fair market value or the cost basis of the item.

How It Works:

• Donate items that are of significant value.

• If the charity can use the item (e.g., donating art to a museum), you may be able to deduct the fair market value.

• If the charity sells the item, the deduction might be based on the cost basis (what you originally paid for it).

Why It’s Smart: Donating tangible items can help you offload valuable but non-liquid assets while benefiting from a tax deduction. It’s a great option if you have personal property you no longer need or want.

5. Use Life Insurance

Using life insurance to donate is a great option if you want to make a significant future donation without needing to use other assets. You can either donate a policy you no longer need or make the charity the beneficiary of a current policy.

How It Works:

• Option 1: Transfer ownership of an existing policy to the charity. You may be able to deduct the policy’s cash value at the time of donation and premiums paid.

• Option 2: Name the charity as a beneficiary on a new or existing life insurance policy, ensuring a future gift.

Why It’s Smart: Donating life insurance allows you to make a larger impact over time, using minimal resources now. If you transfer ownership, you may also receive an immediate tax benefit for the policy’s value and any ongoing premiums paid.

6. Charitable Trusts

For those looking to make a significant impact while also planning for their estate, setting up a charitable trust can be a great way to give. There are different types of charitable trusts, such as Charitable Remainder Trusts (CRTs) and Charitable Lead Trusts (CLTs), which allow you to donate assets while retaining an income stream or passing assets to heirs.

How It Works:

• Set up a trust that holds appreciated assets like stocks or real estate.

• A Charitable Remainder Trust (CRT) provides you or your beneficiaries with income for a set period, and the remainder goes to the charity.

• A Charitable Lead Trust (CLT) directs income to the charity for a set time, after which the remainder goes to your heirs.

Why It’s Smart: Charitable trusts allow you to make a significant contribution while receiving tax benefits and potentially providing for your family. They are a great tool for those with complex financial or estate planning goals.

Final Thoughts

If you’re an investor, donating cash should be your last resort. By giving appreciated securities, real estate, personal property, a life insurance policy or leveraging tools like IRAs or charitable trusts, you can have more money be received by non-profits and realize significant tax advantages. The “give cash last” mentality allows you to do more with what you already have, making a bigger difference for the causes you care about while being smart with your financial resources.  Before you write that next check to charity, consider how some of your investments can reach even further….and get you a bigger tax break.  Want to explore your options? Let’s chat.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

This material and the opinions voiced are for general information only and are not intended to provide specific advice or recommendations for any individual or entity. To determine what is appropriate for you, please contact your Rose Street Financial Professional. Information obtained from third-party sources are believed to be reliable but not guaranteed.  The tax and legal references attached herein are provided with the understanding that neither M Financial Group, nor its Member Firms are engaged in rendering tax, legal, or actuarial services. If tax, legal, or actuarial advice is required, you should consult your accountant, attorney, or actuary. Neither M Financial Group, nor its Member Firms should replace those advisors.

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5354095

Interested in more?

Let's Talk Proactive HR

Unlocking Financial Security: The Power of Qualified Longevity Annuity Contracts (QLACs)

What is a Qualified Longevity Annuity Contract (QLAC)?

A Qualified Longevity Annuity Contract(QLAC) is a type of deferred annuity funded with money from a qualified retirement plan, such as a 401(k) or an IRA. It's designed to provide a guaranteed stream of income later in life, helping to ensure that you don't outlive your retirement savings. 

Top 5 Reasons to Consider a QLAC

1. Guaranteed Income  

QLACs provide a steady, predictable income stream for life, offering financial clarity.   

2. Tax Deferral

Funds used to purchase a QLAC are exempt from required minimum distribution (RMD) rules until payments begin.  

3. Protection Against Longevity Risk 

QLACs help mitigate the risk of outliving your savings. 

4. Flexibility in Start Date 

You can choose when to start receiving payments, typically between 65 and 85.  

5. Simplicity   

Once set up, QLACs require minimal management, making them easy to maintain.   

Drawbacks of QLACs

1. Limited Investment Options   

QLACs typically offer fixed returns, which may be lower compared to other investment options.  

2. Irrevocability

Once purchased, QLACs cannot be easily modified or canceled. 

3. Upfront Costs  

There may be fees and charges associated with purchasing a QLAC.  

4. Lack of Liquidity  

Funds used for a QLAC are not easily accessible until the annuity start date.  

5. Inflation Risk   

If QLACs do not include inflation adjustments, purchasing power may decrease over time.  

Have questions or if this may be right for you, give us a call. 

Scott Higgins | AIF ®, CFP®, CPFA®, NSSA®

Financial Advisor 

Since 2012 at Rose Street, Scott has been responsible for helping the firm’s individual wealth management clients with income strategies for retirement and consulting with employers with their employee retirement plans. In free time, he enjoys golf, biking, skiing, cooking, and traveling. Fun Fact, Scott has a hobby of filling growlers with coins!

Securities and Investment Advisory Services Offered Through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Adviser, Member FINRA/SIPC. Rose Street Advisors is independently owned and operated. #7548799.1

Over the years of working alongside a number of family offices, I continue to be impressed by the sincere care demonstrated for the family (or families) they serve. While we provide life insurance reviews, on-going service and marketplace insight on their current portfolios, we also strategize with family offices on how life insurance can support their overall objectives. After many discussions about the complexities and challenges of running a family office, could life insurance possibly be a “Family Office’s best friend”?

Initiating the Conversation

The process of buying life insurance is one focused on the next generation. As a mentor of mine told me early on, “Two types of people buy life insurance - those who care about someone and those who care about something besides themselves." Especially when working with younger generations, any opportunity to discuss the sense of responsibility they should have to future generations and their family legacy is meaningful. A conversation regarding life insurance planning is another occasion for the family to consider who and what they care most about

A Business Model of Service

My experience with family offices has been an atmosphere of high touch and high service. Family offices are intentional about being advocates for their families; their service model intertwines both the personal and professional workings of a family. In order to do that well, there must be wealth to manage and revenue generated so resources are available to support all those important functions. When family trees branch farther and farther out, the level of wealth can be diluted while the service expectation from each increasing family member remains constant. One way to counter that reality is to intentionally plan for ways to mitigate depleting family wealth; revenue must match expectations and obligations. With careful planning to minimize income and estate taxes, wealth spent over multiple generations is naturally replenished by an injection of life insurance.

Forced Savings Plan

Paying premiums can serve as a savings mechanism for those who depend on future trust dollars and prevent current recipients from leaving little behind. This strategy can help family offices and those in a fiduciary role balance the demands of the current generation with the responsibility to look out for the interests of future generations.

An Asset Without Equal

Life insurance is still the only asset that avoids taxation at all levels and continues to be a vehicle used by wealthy families to accomplish explicit wealth transfer objectives. While GST-exempt Dynasty Trusts may hold a majority of family assets, inevitably there will be situations where assets outside the trust are susceptible to future taxation. Life insurance does not recognize income or gains requiring complex annual tax reporting (cash values grow inside the policy free from current taxation). As a prime example, private placement life insurance (PPLI) provides access to alternative investments, while being tax-efficient and eliminating the need to track down another K-1 or further complicate tax returns. Life insurance may not be as warm and friendly as a golden retriever, but for a family office, at least you don’t have to worry about cleaning the carpets. If you have questions or would like to see how the advisors at Rose Street Advisors can help you better serve your clients, please contact us below. We are here to help. Click here to request a policy review!

Rob Hunt II

LIC & CLU® | Principal & Chief Executive Officer

As Principal and CEO, Rob spearheads the vision, drive for growth, and pursuit of excellence at Rose Street Advisors. Rob loves being outdoors with his wife Erin and kids. He has slalom skied for the past 35 years, never missing a season. He also enjoys spending time at the lake and on the golf course. This material and the opinions voiced are for general information only and are not intended to provide specific advice or recommendations for any individual or entity. To determine what is appropriate for you, please contact your Rose Street Financial Professional. Information obtained from third-party sources are believed to be reliable but not guaranteed. Securities and Investment Advisory: Services offered through M Holdings Securities, Inc., A Registered Broker/Dealer and Investment Advisor, member FINRA/SIPC. Rose Street Advisors is independently owned and operated. Rose Street Advisors is a member firm of M Financial Group. #6610057.1

Interested in more?

Let's Talk Proactive HR
Do you own a business?  Do you want to pass wealth to your business and/or your family?  Do you want to ensure that your business and/or wealth passes to multiple generations?  While the future is uncertain, it is important to plan. When our clients create estate and succession plans, they are limited by the information at hand at this moment; whether that be their current family and business environment, recently updated IRS guidelines, acceptable planning techniques, or current estate and income taxation regulations. Almost all plans will need to extend over numerous decades and multiple generations. Change is not probable, it is inevitable, and that is why liquidity, and the flexibility it provides, will never go out of style.  At Rose Street Advisors, we have the unique opportunity to work alongside our clients and their advisors (attorneys, CPAs, etc.) to safeguard their families and businesses to create a blueprint that meets their planning objectives. As a flexible instrument, life insurance provides unencumbered, tax-efficient liquidity when needed most.  Life insurance is used as a tool to provide funds needed to: • Help divide an illiquid asset among children; such as a family business, farm, or cottage when interest and ability to manage the asset is varied, but a desire to be “fair” is of utmost importance. • Create a guaranteed market for an owner’s business interest so that a spouse is not dependent on the future success of a business. It can also provide a surviving business partner tax-free liquidity necessary to acquire the deceased partner’s interest in the company. • Provide funds that can be used to pay a federal estate tax that comes due within 9 months following the passing of an individual with a large estate exceeding the current estate-tax exemption amount. • Compensate a key employee’s family in full when a deferred benefit has been promised to the deceased. • Provide working capital to a business needing to replace a key member of a company who has unexpectedly passed. Are you facing an uncertain future? We all are, and the only way to get ahead of it is to plan. If you would like to speak with us regarding your situation or how best to use life insurance in your planning process, please contact us. We look forward to your call!

Rob Hunt II

LIC & CLU® | Principal & Chief Executive Officer

As Principal and CEO, Rob spearheads the vision, drive for growth, and pursuit of excellence at Rose Street Advisors. Rob loves being outdoors with his wife Erin and kids. He has slalom skied for the past 35 years, never missing a season. He also enjoys spending time at the lake and on the golf course. This material and the opinions voiced are for general information only and are not intended to provide specific advice or recommendations for any individual or entity. To determine what is appropriate for you, please contact your Rose Street Financial Professional. Information obtained from third-party sources are believed to be reliable but not guaranteed. Securities and Investment Advisory: Services offered through M Holdings Securities, Inc., A Registered Broker/Dealer and Investment Advisor, member FINRA/SIPC. Rose Street Advisors is independently owned and operated. Rose Street Advisors is a member firm of M Financial Group. #6519084.1

Interested in more?

Let's Talk Proactive HR
Rose Street Advisors

Your guide from hire to retire. Rose Street Advisors provides the strategy companies need to grow with confidence.

Firm
About UsOur TeamCommunity SupportTestimonials
Services
Employee BenefitsHR ConsultingLife InsuranceEmployer Retirement PlansWealth ManagementFiduciary Fitness
Contact

244 North Rose Street
Kalamazoo, MI 49007

5181 Plainfield Ave NE
Grand Rapids, MI 49525

269.552.3200
© 2026 Rose Street Advisors LLC. All rights reserved.
Securities and Investment Advisory Services Offered Through M Holdings Securities, Inc. A Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors is independently owned and operated. Please go to www.mfin.com/DisclosureStatement for further details regarding this relationship. Check the background of this Firm and/or investment professional on FINRA's BrokerCheck. For important information related to M Securities, refer to the M Securities' Client Relationship Summary (Form CRS) by navigating to mfin.com/m-securities. Registered Representatives are registered to conduct securities business and licensed to conduct insurance business in limited states. Response to, or contact with, residents of other states will only be made upon compliance with applicable licensing and registration requirements. The information in this website is for U.S. residents only and does not constitute an offer to sell, or a solicitation of an offer to purchase brokerage services to persons outside of the United States. This site is for information purposes and should not be construed as legal or tax advice and is not intended to replace the advice of a qualified attorney, financial or tax advisor or plan provider. CA Insurance License. File #5757992.1

We value your privacy

We use cookies to keep this site reliable, understand how it’s used, and — with your permission — to personalize content. You can accept all, reject non-essential, or choose which categories to allow.

Privacy Policy

Cookie Preferences