Rose Street Advisors Rose Street Advisors
Firm
About UsOur TeamM Financial GroupEducation LibraryCommunity SupportTestimonials
Benefits
Employee Benefit ServicesBenefits FAQBenefits University Blog
HR Consulting
HR Consulting ServicesHR BlogRose Street Recruits
Life Insurance
Life Insurance ServicesLife Happens BlogLife Insurance Vlog
Employer Retirement Plans
Retirement ServicesFiduciary Fitness ProgramGuide to Retirement BlogRetirement Plans FAQ
Wealth Management
Wealth Management ServicesInvestED BlogWealth Management FAQs
Get In Touch
Firm
About UsOur TeamM Financial GroupEducation LibraryCommunity SupportTestimonials
Benefits
Employee Benefit ServicesBenefits FAQBenefits University Blog
HR Consulting
HR Consulting ServicesHR BlogRose Street Recruits
Life Insurance
Life Insurance ServicesLife Happens BlogLife Insurance Vlog
Employer Retirement Plans
Retirement ServicesFiduciary Fitness ProgramGuide to Retirement BlogRetirement Plans FAQ
Wealth Management
Wealth Management ServicesInvestED BlogWealth Management FAQs
Get In Touch

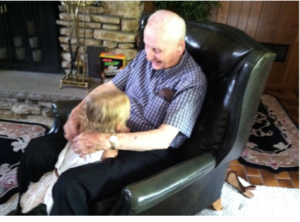
The pic is a little blury, but one that we will never get rid of.  We knew the end with my Grandpa was near, but didn’t know how near.  This was the last picture we have of my Grandpa and my oldest.  The look on his face tells the story.  He loved this moment!  He was an incredible man of faith, lover of kids and quiet powerhouse of a leader.  He led by serving people.  What a joy to have my daughter get a chance to spend a couple years with him before he passed away.  He and my Grandma were married for 66 years and led a life serving others.  They died within 8 months of each other.  What a legacy they built and left.

When a parent’s health is declining and the end may be near, families often feel two things at the same time. Emotionally, you want to be present. Practically, you know there are things that should be handled. This guide is meant to help you do both. You do not need to do everything at once.  You just need to start.

1. Have the Most Important Conversation

If your parent is able, this is the most valuable step.

Discuss
• Who makes medical decisions
• Who handles finances
• Care preferences (hospice, hospital, life support)
• Funeral wishes
• Where documents are located
• How assets should be handled
• Who communicates with family

Checklist
☐ Identify medical decision maker
☐ Identify financial decision maker
☐ Discuss care preferences
☐ Discuss funeral wishes
☐ Ask where documents are located

  1. Confirm Legal Documents

These allow you to act before death, not just after.

Important documents
• Will or trust
• Financial power of attorney
• Healthcare power of attorney
• Living will / advance directive
• HIPAA authorization
• Beneficiary designations

Double check life insurance beneficiaries. These override a will and are often outdated.

Checklist
☐ Locate will or trust
☐ Confirm financial POA
☐ Confirm healthcare POA
☐ Confirm advance directive
☐ Review retirement beneficiaries
☐ Review life insurance beneficiaries

  1. Identify Decision Makers

You should know:
• Medical decision maker
• Financial decision maker
• Executor
• Family communicator

Checklist
☐ Identify roles
☐ Share roles with family

  1. Gather Financial Information

You are simply identifying what exists.

Include
• Bank accounts
• Investment accounts
• Retirement accounts
• Life insurance
• Annuities
• Real estate
• Debts

Checklist
☐ List accounts
☐ List insurance
☐ List debts
☐ Gather statements

  1. Contact the Financial Advisor

They can help organize everything and prepare for what comes next.

They help with
• Account list
• Beneficiaries
• Life insurance review
• What avoids probate
• Liquidity needs
• Next steps

Checklist
☐ Notify advisor
☐ Request account list
☐ Confirm beneficiaries
☐ Double check life insurance beneficiaries
☐ Ask what to prepare now

  1. Understand What Transfers Automatically

Some assets transfer immediately
• Life insurance with beneficiary
• Retirement accounts with beneficiary
• Joint accounts
• Trust assets

Others may require probate
• Assets in one name
• No beneficiary
• No trust

Checklist
☐ Identify beneficiary accounts
☐ Identify probate assets

  1. Discuss the Home

This is often the largest decision.

Discuss
• Keep or sell
• Who maintains it
• Where documents are
• Mortgage and insurance

Checklist
☐ Discuss home plan
☐ Locate deed
☐ Confirm insurance

  1. Discuss Funeral Preferences

Consider
• Burial or cremation
• Funeral home
• Service preferences
• Cemetery
• Obituary

Checklist
☐ Burial vs cremation
☐ Funeral home
☐ Service preferences

  1. Determine How Expenses Will Be Paid

This prevents stress immediately after death.

Identify
• Life insurance
• Prepaid funeral plans
• Liquid accounts
• Who pays upfront expenses

Checklist
☐ Identify life insurance
☐ Confirm beneficiaries
☐ Identify liquid fund
☐ Determine who pays upfront

  1. Gather Digital Access

Often overlooked but extremely helpful.

Include
• Phone passcode
• Email access
• Financial logins
• Subscriptions
• Social media

Checklist
☐ Document phone access
☐ Document email access
☐ Document financial logins

  1. Create a Simple Information Sheet

Include
• Full name
• Social Security number
• Date of birth
• Advisor contact
• Attorney contact
• Account list
• Document locations

Checklist
☐ Create information sheet
☐ Share with trusted person

  1. Share Document Locations

Make sure the right people know where everything is.

Checklist
☐ Share document locations
☐ Provide copies to decision makers
☐ Confirm safe deposit box access

Where to Start First

☐ Have the conversation
☐ Identify decision makers
☐ Locate will and documents
☐ Double check life insurance beneficiaries
☐ Contact financial advisor
☐ List accounts
☐ Discuss funeral wishes
☐ Determine expense funding

You do not need to do everything today. You just need to begin.

About Rose Street Advisors Wealth Management

At Rose Street Advisors Wealth Management, we often walk alongside families during life’s most difficult transitions. When a parent’s health is declining, decisions become both emotional and practical. Many families are unsure what should be handled now versus later.

Our role is to bring clarity and calm during an uncertain time. We help families organize accounts, review beneficiaries, coordinate with attorneys, identify what will transfer smoothly, and prepare for the decisions that follow. Just as importantly, we help families avoid rushed decisions and focus on what matters most.

Planning ahead does not make this season easier emotionally, but it can remove uncertainty and reduce stress for everyone involved.

If your family is navigating this stage, we would be honored to help you think through next steps, answer questions, or simply provide guidance.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5350478

Interested in more?

Let's Talk Proactive HR

1. Protect your family

2. Protect your business partners

3. Protect your employees

It doesn’t have to be anymore complicated or complex than the fundamental reasons listed above. A person's income and their ability to continue to earn an income in the future is their most valuable asset. Disability/Income Replacement Insurance protects a person’s ability to earn income if they become physically or mentally unable to work.  This type of coverage allows a person to continue to provide for their family by still receiving an income, it allows business partners to protect each other’s interests in the case a partner’s disability disrupts business and it may prevent an employer from hastily selling his/her business in case of a disabling event.    

As a valued executive benefit for your high-income earners, additional Disability/Income Replacement Insurance can be an easy add-on to complement your existing group long-term disability plans. If you have any questions or would like to connect with a Rose Street Advisor, please contact us today.

Rob Hunt II

LIC & CLU® | Principal & Chief Executive Officer

As Principal and CEO, Rob spearheads the vision, drive for growth, and pursuit of excellence at Rose Street Advisors. Rob loves being outdoors with his wife Erin and kids. He has slalom skied for the past 35 years, never missing a season. He also enjoys spending time at the lake and on the golf course.

This material and the opinions voiced are for general information only and are not intended to provide specific advice or recommendations for any individual or entity. To determine what is appropriate for you, please contact your Rose Street Financial Professional. Information obtained from third-party sources are believed to be reliable but not guaranteed.


Securities and Investment Advisory: Services offered through M Holdings Securities, Inc., A Registered Broker/Dealer and Investment Advisor, member FINRA/SIPC. Rose Street Advisors is independently owned and operated. Rose Street Advisors is a member firm of M Financial Group. #4491815

Interested in more?

Let's Talk Proactive HR

The IRS is at it again! Partnerships should take notice.

While the case has drawn some attention by the advisor network, this ruling is worth another look. The 8th Circuit Court of Appeals finding in the Connelly Case was affirmed by the U.S. Supreme Court on June 6, 2024. In this case, the buy-sell liability offset was not recognized by the court and thus the corporately-owned life insurance paid at death significantly increased the value of the deceased’s estate and resulting estate-tax. Although the decision focused exclusively on Stock Redemption Agreements in the 8th Circuit Court jurisdiction, regardless of location, all business owners should take notice and consider a review of their existing buy-sell agreements and funding mechanisms. 

Previous Next

Rob Hunt II

LIC & CLU® | Principal & Chief Executive Officer

As Principal and CEO, Rob spearheads the vision, drive for growth, and pursuit of excellence at Rose Street Advisors. Rob loves being outdoors with his wife Erin and kids. He has slalom skied for the past 35 years, never missing a season. He also enjoys spending time at the lake and on the golf course.

This material and the opinions voiced are for general information only and are not intended to provide specific advice or recommendations for any individual or entity. To determine what is appropriate for you, please contact your Rose Street Financial Professional. Information obtained from third-party sources are believed to be reliable but not guaranteed.


Securities and Investment Advisory: Services offered through M Holdings Securities, Inc., A Registered Broker/Dealer and Investment Advisor, member FINRA/SIPC. Rose Street Advisors is independently owned and operated. Rose Street Advisors is a member firm of M Financial Group. #6772299.1

Interested in more?

Let's Talk Proactive HR
Over the years of working alongside a number of family offices, I continue to be impressed by the sincere care demonstrated for the family (or families) they serve. While we provide life insurance reviews, on-going service and marketplace insight on their current portfolios, we also strategize with family offices on how life insurance can support their overall objectives. After many discussions about the complexities and challenges of running a family office, could life insurance possibly be a “Family Office’s best friend”?

Initiating the Conversation

The process of buying life insurance is one focused on the next generation. As a mentor of mine told me early on, “Two types of people buy life insurance - those who care about someone and those who care about something besides themselves." Especially when working with younger generations, any opportunity to discuss the sense of responsibility they should have to future generations and their family legacy is meaningful. A conversation regarding life insurance planning is another occasion for the family to consider who and what they care most about

A Business Model of Service

My experience with family offices has been an atmosphere of high touch and high service. Family offices are intentional about being advocates for their families; their service model intertwines both the personal and professional workings of a family. In order to do that well, there must be wealth to manage and revenue generated so resources are available to support all those important functions. When family trees branch farther and farther out, the level of wealth can be diluted while the service expectation from each increasing family member remains constant. One way to counter that reality is to intentionally plan for ways to mitigate depleting family wealth; revenue must match expectations and obligations. With careful planning to minimize income and estate taxes, wealth spent over multiple generations is naturally replenished by an injection of life insurance.

Forced Savings Plan

Paying premiums can serve as a savings mechanism for those who depend on future trust dollars and prevent current recipients from leaving little behind. This strategy can help family offices and those in a fiduciary role balance the demands of the current generation with the responsibility to look out for the interests of future generations.

An Asset Without Equal

Life insurance is still the only asset that avoids taxation at all levels and continues to be a vehicle used by wealthy families to accomplish explicit wealth transfer objectives. While GST-exempt Dynasty Trusts may hold a majority of family assets, inevitably there will be situations where assets outside the trust are susceptible to future taxation. Life insurance does not recognize income or gains requiring complex annual tax reporting (cash values grow inside the policy free from current taxation). As a prime example, private placement life insurance (PPLI) provides access to alternative investments, while being tax-efficient and eliminating the need to track down another K-1 or further complicate tax returns. Life insurance may not be as warm and friendly as a golden retriever, but for a family office, at least you don’t have to worry about cleaning the carpets. If you have questions or would like to see how the advisors at Rose Street Advisors can help you better serve your clients, please contact us below. We are here to help. Click here to request a policy review!

Rob Hunt II

LIC & CLU® | Principal & Chief Executive Officer

As Principal and CEO, Rob spearheads the vision, drive for growth, and pursuit of excellence at Rose Street Advisors. Rob loves being outdoors with his wife Erin and kids. He has slalom skied for the past 35 years, never missing a season. He also enjoys spending time at the lake and on the golf course. This material and the opinions voiced are for general information only and are not intended to provide specific advice or recommendations for any individual or entity. To determine what is appropriate for you, please contact your Rose Street Financial Professional. Information obtained from third-party sources are believed to be reliable but not guaranteed. Securities and Investment Advisory: Services offered through M Holdings Securities, Inc., A Registered Broker/Dealer and Investment Advisor, member FINRA/SIPC. Rose Street Advisors is independently owned and operated. Rose Street Advisors is a member firm of M Financial Group. #6610057.1

Interested in more?

Let's Talk Proactive HR
Do you own a business?  Do you want to pass wealth to your business and/or your family?  Do you want to ensure that your business and/or wealth passes to multiple generations?  While the future is uncertain, it is important to plan. When our clients create estate and succession plans, they are limited by the information at hand at this moment; whether that be their current family and business environment, recently updated IRS guidelines, acceptable planning techniques, or current estate and income taxation regulations. Almost all plans will need to extend over numerous decades and multiple generations. Change is not probable, it is inevitable, and that is why liquidity, and the flexibility it provides, will never go out of style.  At Rose Street Advisors, we have the unique opportunity to work alongside our clients and their advisors (attorneys, CPAs, etc.) to safeguard their families and businesses to create a blueprint that meets their planning objectives. As a flexible instrument, life insurance provides unencumbered, tax-efficient liquidity when needed most.  Life insurance is used as a tool to provide funds needed to: • Help divide an illiquid asset among children; such as a family business, farm, or cottage when interest and ability to manage the asset is varied, but a desire to be “fair” is of utmost importance. • Create a guaranteed market for an owner’s business interest so that a spouse is not dependent on the future success of a business. It can also provide a surviving business partner tax-free liquidity necessary to acquire the deceased partner’s interest in the company. • Provide funds that can be used to pay a federal estate tax that comes due within 9 months following the passing of an individual with a large estate exceeding the current estate-tax exemption amount. • Compensate a key employee’s family in full when a deferred benefit has been promised to the deceased. • Provide working capital to a business needing to replace a key member of a company who has unexpectedly passed. Are you facing an uncertain future? We all are, and the only way to get ahead of it is to plan. If you would like to speak with us regarding your situation or how best to use life insurance in your planning process, please contact us. We look forward to your call!

Rob Hunt II

LIC & CLU® | Principal & Chief Executive Officer

As Principal and CEO, Rob spearheads the vision, drive for growth, and pursuit of excellence at Rose Street Advisors. Rob loves being outdoors with his wife Erin and kids. He has slalom skied for the past 35 years, never missing a season. He also enjoys spending time at the lake and on the golf course. This material and the opinions voiced are for general information only and are not intended to provide specific advice or recommendations for any individual or entity. To determine what is appropriate for you, please contact your Rose Street Financial Professional. Information obtained from third-party sources are believed to be reliable but not guaranteed. Securities and Investment Advisory: Services offered through M Holdings Securities, Inc., A Registered Broker/Dealer and Investment Advisor, member FINRA/SIPC. Rose Street Advisors is independently owned and operated. Rose Street Advisors is a member firm of M Financial Group. #6519084.1

Interested in more?

Let's Talk Proactive HR
Rose Street Advisors

Your guide from hire to retire. Rose Street Advisors provides the strategy companies need to grow with confidence.

Firm
About UsOur TeamCommunity SupportTestimonials
Services
Employee BenefitsHR ConsultingLife InsuranceEmployer Retirement PlansWealth ManagementFiduciary Fitness
Contact

244 North Rose Street
Kalamazoo, MI 49007

5181 Plainfield Ave NE
Grand Rapids, MI 49525

269.552.3200
© 2026 Rose Street Advisors LLC. All rights reserved.
Securities and Investment Advisory Services Offered Through M Holdings Securities, Inc. A Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors is independently owned and operated. Please go to www.mfin.com/DisclosureStatement for further details regarding this relationship. Check the background of this Firm and/or investment professional on FINRA's BrokerCheck. For important information related to M Securities, refer to the M Securities' Client Relationship Summary (Form CRS) by navigating to mfin.com/m-securities. Registered Representatives are registered to conduct securities business and licensed to conduct insurance business in limited states. Response to, or contact with, residents of other states will only be made upon compliance with applicable licensing and registration requirements. The information in this website is for U.S. residents only and does not constitute an offer to sell, or a solicitation of an offer to purchase brokerage services to persons outside of the United States. This site is for information purposes and should not be construed as legal or tax advice and is not intended to replace the advice of a qualified attorney, financial or tax advisor or plan provider. CA Insurance License. File #5757992.1

We value your privacy

We use cookies to keep this site reliable, understand how it’s used, and — with your permission — to personalize content. You can accept all, reject non-essential, or choose which categories to allow.

Privacy Policy

Cookie Preferences